
CPA-led accounting for electricians, plumbers and contractors in York Region
Know what every job is really making.
Books, HST, payroll and tax handled by a CPA who works only with trades. I start when you’re a one-truck shop, and I’m still there when the bank and the bonding company start asking for statements.
30 minutes, by video or at your shop. You keep the written findings either way.
| Job | Price | Hours | Net profit | Margin |
|---|---|---|---|---|
| Panel upgrade, 200A | 3,800 | 16 | 606 | 16% |
| Basement rough-in | 6,200 | 48 | (642) | (10%) |
| Generator install | 9,800 | 40 | 1,730 | 18% |
| Service call, no power | 450 | 3.5 | 54 | 12% |
| Month | 20,250 | 107.5 | 1,748 | 8.6% |
Sound familiar?
The first three happen in every one-truck shop. The last three happen the moment it grows.
What I take off your plate
One CPA, all of your accounting, in one place. Start with what you need now; the rest is there when you grow.
The monthly file
Bookkeeping in QuickBooks Online, bank and cards reconciled, every job coded so you can see what it made. HST filed on time, with holdback timing done right. The truck, the tools and the subcontractors handled the way CRA expects. Payroll and WSIB when you have a crew. A monthly P&L you can read in two minutes.
Year-end and tax
Financial statements compiled with the working papers behind them. The corporate T2 and the owner’s personal T1, filed here. T4s and T5018 slips out by the deadline. CRA and WSIB letters answered before they become problems.
Pricing and paying yourself
The labour rate you need to charge once overhead is counted, and which jobs are quietly losing money. Salary, dividends or a mix, worked out each year so you keep more of what the company makes.
Bonding and the bankWhen you grow
The WIP schedule with over and under billings. Statements built the way lenders and sureties read them, delivered on their calendar, not after it. Credit-line and bonding-capacity models when you’re going after more room.
Review and audit readinessWhen you grow
When your surety or lender asks for reviewed or audited statements, a licensed public accounting firm performs that engagement. I prepare the file, reconcile the schedules and work the request list so it is fast and clean.
How I work
01
The call
Thirty minutes, free, by video or at your shop. I ask where the company is and where you want to take it, and look at the books, the filings and the last year-end. You get a short written note: what’s exposed, what it’s costing you, and what I’d fix first.
02
The build
Cleanup and catch-up filings. QuickBooks set up so every job and every truck is coded properly from day one. For growing shops, the WIP schedule built from your estimates and contracts.
03
The rhythm
A monthly close with the job report, and a call when the numbers need one. Statements by the fifteenth. HST, payroll and slips filed on time, every time.
04
Nothing lives in one head
The file is yours and you can see it any time. Whoever helps you in the office, a spouse, a bookkeeper, a manager later on, learns what a clean month looks like, so the books never depend on one person. Including me.
Is this a fit?
This is for you if
You are an electrician, plumber, HVAC, general or specialty contractor in York Region or nearby.
You are a one-truck shop that wants the books and taxes done right and wants to know which jobs made money, or a growing company whose bank, surety or next bid is asking for real numbers.
You are incorporated, or about to be.
You want one accountant who handles all of it, from the monthly file to the year-end, and is still there when the company gets bigger.
This is not for you if
You are outside the trades. Contractors are the only clients I take.
You want the cheapest return filed and nothing more.
You are pre-revenue, or you need a licensed audit firm rather than an accountant who prepares the file for one.
No hard feelings on any of these. I would rather say so on the first call than three months in.
Packages
Flat monthly fees, confirmed in writing after a 30-minute call. Every package includes the year-end, the T2 and the owner’s personal return. You move up when the company does, with the same accountant and the same file.
Start here
Trades Starter
Taxes done, books clean, no April surprise.
$375 / month, flat
One to three trucks, under $600K. You’re on the tools and want it handled.
- Monthly books in QuickBooks Online, bank and cards reconciled
- HST filed on time, holdback timing done right
- Monthly P&L you can read in two minutes
- Job profit report every quarter
- Year-end statements, T2, owner’s T1, salary vs dividend worked out
- T4s and T5018 slips; CRA letters answered
- Email reply within one business day
Foundation
Stay compliant, no surprises.
from $950 / month
$600K to $1.5M, a crew on payroll, subs to keep straight.
- Everything in Trades Starter, numbers current within 30 days
- Payroll for the owner and crew
- T5018 slips, WSIB clearances, worker classification
- Job profit report every quarter
- Annual tax planning session and pay-mix plan
- CRA and WSIB letters, reviews and audits handled
- Quarterly check-in, two-business-day response
Most growing shops land here
Framework
Know what every job is making.
from $1,750 / month
$1.5M and up. Progress billing, a bank line, bonding on the horizon or in place.
- Everything in Foundation, numbers current within two weeks
- Job profit report every month
- Compiled financial statements with a compilation engagement report; T1s for all shareholders
- Bank and surety reporting: WIP schedule, covenant monitoring, lender and surety packages
- Get-paid management: progress billing, holdback receivables, prompt-payment deadlines
- 13-week cash-flow forecast; KPI scorecard reviewed quarterly
- Monthly strategy call, next-business-day response, one site visit a year
Which one? What I’d suggest
You and a helper, under $600K: Trades Starter. The value is the taxes and the quarterly job report; anything more is paying for reports you won’t read yet.
A crew on payroll, subs, $600K to $1.5M: Foundation. Payroll, WSIB and T5018s are where small shops get hurt, and this covers them.
Progress billing, a bank line or a surety, $1.5M and up: Framework. Monthly job margins and get-paid management usually pay for the fee in collected holdbacks alone. Past $4M, or with covenants reviewed every year, I add CFO time and quote it with the package.
What the bank and your bonding company actually read
Every one of these comes straight off your financial statements. That is why the statements matter more than the loan or bond application.
Working capital
Current assets less current liabilities, with holdbacks and over-billings treated the way the lender treats them.
Tangible net worth
Equity after shareholder loans and intangibles are stripped out. Often the number that caps your line or your bond program.
The WIP schedule
Job-by-job margin and over and under billings. The first thing a surety analyst turns to, and the first thing that is usually missing.
Consistency
The same statements, on the same basis, on time, every year. Late or restated numbers cost capacity even when the business is sound.
Not bonded yet? The same four numbers decide your next truck loan and your first credit line. Start the books properly on day one and they are already in shape when the bigger work shows up.
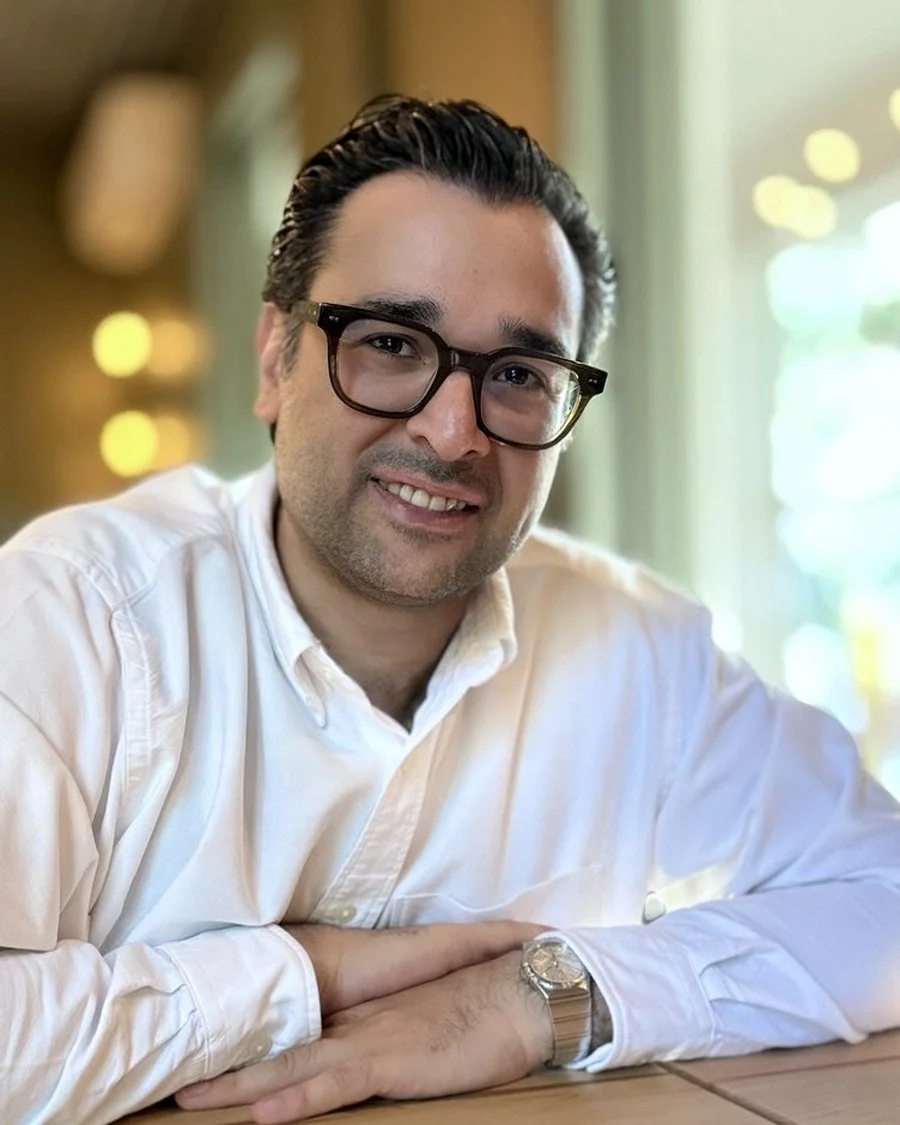
I have never been the accountant who visits once a year.
I’m Peyman, a CPA in Aurora and the founder of PS Accounting Studio. Before starting the practice I spent fifteen years inside operating businesses closing the month, including rebuilding a company’s finance function ahead of an audit and an acquisition, and leading finance at an Ontario regulator.
I have been the one waiting on the auditor’s request list, and the one explaining why the income statement says profit while the bank account disagrees. That is the experience I bring to your books, and it is why I know what the bank, the surety and CRA are going to ask before they ask it.
Today PS Accounting Studio does the accounting for a bonded mechanical contractor: the monthly close, the year-end, and the WIP and covenant reporting the surety and the bank ask for, including the numbers behind their most recent credit-line increase. That company started as one truck too. The books I set up for a shop at $300K are built so they still work at $3M.
My background is industry, not audit practice. I work in English and Farsi, and I come to the shop.
Three things you can use today
Starting out
The Job Profit Calculator
Enter the quote, the hours and the materials and see what a job actually made once the truck, insurance and your own office time are counted. Two minutes. Most shops find their service calls are under water.
Get the calculatorFree Excel file. Downloads as soon as you fill in the short form.
Growing
The Contractor Profit Leak Checklist
The seven places margin disappears between the estimate and the bank account, and the one report that catches each of them.
Send me the checklistIt arrives by email, usually the same day.
Bidding and bonding
The Bondability Checklist
The items a surety checks before issuing a first bond or increasing a program, and how to score your own file against them. No email required, and brokers are welcome to send it to clients.
Download the checklist (PDF)Free PDF. Nothing to sign up for.
There is more in the library. Templates, short notes and all three tools, with a new item added every month.
Browse all resourcesQuestions contractors ask
I’m a one-truck shop. Is $375 a month really everything?
Yes. Monthly books, HST, the year-end statements, the corporate T2 and your personal T1, T4s and T5018s, and a job profit report every quarter. Payroll for employees, a cleanup of prior years, or more than about 150 transactions a month are quoted up front before anything starts. No hourly billing, no surprise invoice in April.
My books are a mess and I’m behind on filings. Can you still take me?
That’s most new clients. The cleanup and catch-up is quoted as a one-time project before we begin, so you know the number, and the monthly fee starts once the file is current. Being behind is a reason to call, not a reason to wait.
Do I have to leave my current accountant?
Not on day one. Some clients start with the monthly books and the job report and keep their current accountant for the year-end until they see the difference. When you’re ready to move the year-end too, I request the file and the working papers and the switch takes a couple of weeks. Nothing gets refiled.
My spouse does the invoicing. Can that stay?
Yes, and it usually should. Whoever is already in the file keeps doing what they do; I set it up so the coding is right, review it each month, and take everything above it: HST, year-end, tax, and the reports.
Do I need to be incorporated?
No. Sole proprietors are welcome; the year-end is a T1 with business income instead of a T2. When incorporating starts to save you money, usually once there’s profit you don’t need to take out of the business, I’ll tell you and handle it.
Do you handle personal tax for the owner?
Yes, the owner’s T1 is included in every package, and salary versus dividends is worked out each year before anything is paid, not after. A spouse’s return is a small add-on.
How do you handle HST on holdbacks?
HST on a holdback isn’t due until the holdback is due to you, so it shouldn’t be remitted when you invoice the progress billing. Most general bookkeeping remits it early, which means you’re lending CRA your cash for months. I track holdback receivables separately and file the HST when it’s actually owed.
Do you file T5018s, and who has to be on them?
Yes. If your business is mainly construction and you paid a subcontractor more than $500 in the year for construction services, they go on a T5018. That includes the guy you paid cash, and it includes materials billed with labour. I keep the list current through the year so February isn’t a scramble.
My surety wants reviewed statements. Can you do that?
When your surety or lender asks for reviewed or audited statements, a licensed public accounting firm performs that engagement. I prepare the file, reconcile the schedules and work the request list so it is fast and clean, and I stay in the conversation with the surety throughout.
What software do you use?
QuickBooks Online for the books, with each job tracked so the profit report comes straight out of it. You keep whatever you already use for quoting, scheduling and invoicing; I connect to it rather than making you switch.
How quickly can you start?
We talk this week, you have a written note and a quote within two business days of the call, and the file is usually set up within two to four weeks. If you’re behind on filings, those go first.
Start with a 30-minute call.
No charge, by video or at your shop. You’ll leave knowing where the books stand, what I’d fix first, and what it would cost to hand them over. You keep the written note whether or not we work together.